Does a stay-at-home parent need life insurance?
A stay-at-home parent's work has real value. Learn what it would cost to replace childcare and household work, and how to choose a life insurance amount.
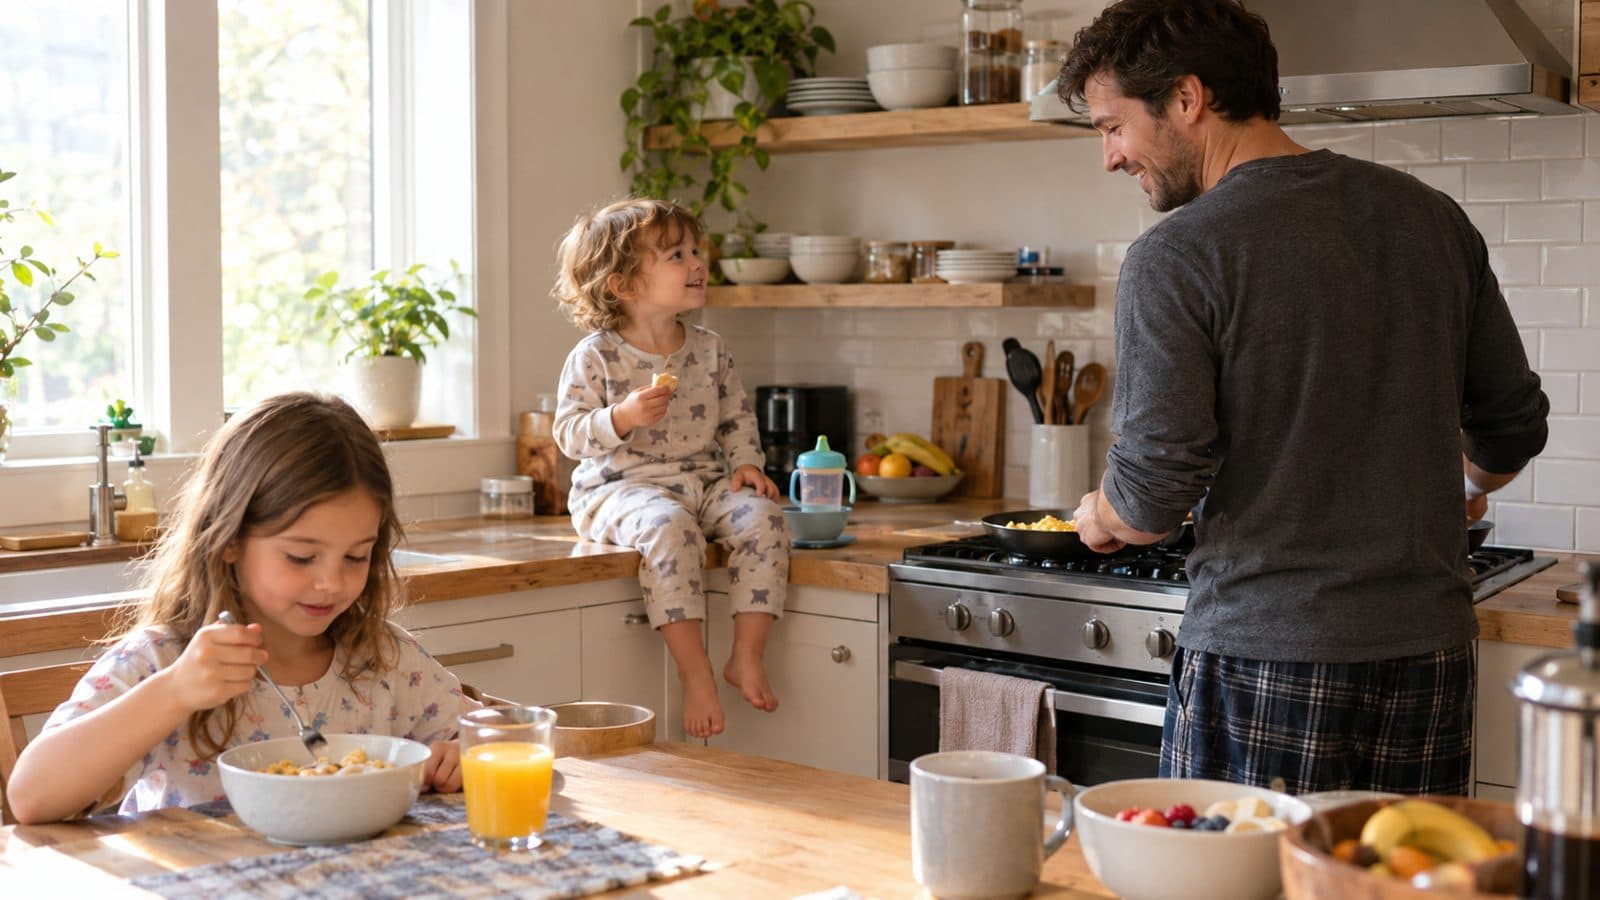
Yes, in many families a stay-at-home parent needs life insurance. They don't bring home a paycheck, but the childcare, driving, cooking and household work they do would cost real money to replace. A term policy can give the working parent room to pay for help, take time off and keep the kids' routine steady.
Skip ahead and check my priceWhy would a parent without a paycheck need life insurance?
Life insurance pays your family when you die so they can cover what you used to provide. For a working parent, that's mostly income. For a stay-at-home parent, it's time, care and a long list of daily jobs.
If that parent dies, the family doesn't lose a salary. They gain a stack of new bills. Someone has to watch the kids, get them to school, cook, clean, manage appointments and handle all the small things that used to happen quietly in the background.
What is a stay-at-home parent's work actually worth?
There's no single official price tag, and estimates you see online vary a lot. A better approach is to look at the time involved and what similar help costs where you live.
Here's what federal data shows:
- Time: In 2024, adults who were not employed and lived with a child under 6 spent about 3.6 hours a day caring for and helping household members, plus about 3.2 hours a day on household activities like cooking and cleaning, according to the Bureau of Labor Statistics. That's nearly seven hours a day, averaged across every day of the week.
- Childcare: The U.S. Department of Labor found that in 2022, full-day childcare for one child cost families between $6,552 and $15,600 a year, or 8.9% to 16% of median family income, depending on location and type of care (U.S. Department of Labor, Women's Bureau).
Those childcare numbers are for one child, and they don't include evenings, sick days, summer breaks, transportation or anything around the house. For many families, the real cost of replacing a stay-at-home parent is a lot higher than daycare alone.
What would it actually cost to replace their work?
It helps to list the jobs and think about who would do them. Your answers will be personal, and that's the point.
| Task | Who might cover it | How to estimate the cost |
|---|---|---|
| Daytime childcare | Daycare, nanny or family help | Call local providers for rates |
| School pickups and activities | Sitter, after-school program, rideshare | Weekly hours times local hourly rate |
| Meals and groceries | Meal kits, takeout, more prepared food | Compare to your current food budget |
| Cleaning and laundry | Cleaning service | Get a quote for weekly or biweekly visits |
| Household management | The surviving parent, with less time to work | Lost income from cutting hours |
| Emotional support | Counseling for kids or the surviving parent | Ask your insurance plan about coverage |
Don't forget the working parent's career. Many surviving parents cut hours to be there for the kids, and that lost income is part of what a policy can replace.
How much life insurance should a stay-at-home parent have?
There's no one right number. The National Association of Insurance Commissioners lists day-care costs, monthly bills, debts and college tuition among the things to think through when choosing an amount.
A simple way to start:
- Estimate the yearly cost of replacing the work using the table above.
- Multiply by the years of need, usually until your youngest child is in school full time or fairly independent.
- Add shared debts you'd want paid down, like part of a mortgage.
- Add final expenses and a cushion for the surviving parent's time off.
Here's a made-up example to show the math. If you estimate $25,000 a year in replacement help and your youngest is 6, you might plan for 12 years of help, or $300,000, plus a cushion. Your numbers will be different, and that's okay.
For a deeper walk-through, try our guide on how to calculate your life insurance needs. If you'd like a starting point right now, you can see what coverage could cost you in a few minutes.
Will Social Security fill the gap?
It may help, but it's usually not enough on its own. Social Security survivor benefits are paid based on the deceased person's own work record (Social Security Administration). A parent who has spent years out of the paid workforce may leave smaller benefits than the family expects.
Think of survivor benefits as one possible piece of the plan, not the whole thing.
Which type of policy makes sense?
Many families choose term life insurance for a stay-at-home parent because the need is tied to a specific stretch of years. Once the kids are grown, the cost of replacing that daily work drops a lot. You can learn more in what is term life insurance and how long your term should be.
It also makes sense to look at both parents together. Ask:
- If the working parent died, could the family get by?
- If the stay-at-home parent died, could the working parent keep working and still care for the kids?
- Are the beneficiaries on each policy set up the way you want? (Here's how beneficiaries work.)
If your family is new to all this, our guide to life insurance for new parents covers the basics. And if you're also wondering whether the working parent's job coverage is enough, see is life insurance through work enough?
How do you get covered without a big hassle?
Evoro Life helps people get term life insurance online and connects them with licensed insurance agents. Policies are applied for through Symetra's SwiftTerm online application and issued by Symetra Life Insurance Company, which has an A.M. Best financial strength rating of A (Excellent).
Coverage is available up to $5 million, and there's no medical exam for most applicants. The application takes about 18 minutes, and quotes are held for 30 days. Coverage isn't available in New York or South Carolina. Approval and pricing depend on underwriting.
Ready to run your numbers? Check your price, or call a licensed agent for free help at (732) 630-1963.
Key takeaways
- A stay-at-home parent's work has real dollar value, even without a paycheck.
- Childcare alone ran $6,552 to $15,600 a year for one child in 2022, before counting driving, meals and housework.
- Estimate the yearly cost of replacing their work, then multiply by the years your kids will need that help.
- Social Security survivor benefits are based on the deceased person's work record and may be limited.
- Term life insurance is a common fit because the need is highest while kids are young.
Frequently asked questions
Does a stay-at-home parent need life insurance if the working parent is already covered?
Often, yes. The working parent's policy protects the family if the paycheck stops, but it does nothing if the stay-at-home parent dies. In that case the family keeps the income but suddenly has to pay for childcare, transportation and household help. A separate policy on the stay-at-home parent covers that gap.
How much life insurance should a stay-at-home parent get?
Start with what it would cost each year to replace their work, like childcare, school pickups, meals and cleaning, then multiply by the number of years until your youngest child is fairly independent. Add any shared debts or final expenses you want covered. A licensed agent can help you test your numbers.
Can you get life insurance if you don't have an income?
Many people without a paycheck can apply for term life insurance, especially when they're married to or partnered with someone who earns income. Approval and the amount offered depend on underwriting. It helps to explain the household's situation when you apply.
Will Social Security help if a stay-at-home parent dies?
Social Security survivor benefits are based on the work record of the person who died. A parent who has been out of the paid workforce for a long time may leave smaller benefits than the family expects, or none. You can check a personal earnings record through a my Social Security account.
Is term or permanent life insurance better for a stay-at-home parent?
Many families use term life insurance here because the need is temporary. The heaviest costs of replacing a parent's work happen while the kids are young, and term coverage can be matched to those years. Term policies also tend to cost less for the same amount of coverage.
Ready to Get Covered?
Apply in as little as 18 minutes, with no medical exam for most applicants. Your quote is held for 30 days, and licensed agents are here if you have questions.
Check my priceNo obligations. No hassle. Just fast, affordable protection for your family.
Written by the Evoro Life Team
The Evoro Life team writes plain-language guides to help people understand term life insurance. This article is general education, not financial, tax or legal advice. For help with your own situation, talk to a licensed agent at (732) 630-1963.
Related Articles
Life insurance for women: what's different and what to know
Why women often pay less for life insurance, why many are underinsured, and how marriage, kids, divorce, caregiving and business ownership change your needs.
Is SGLI enough life insurance for military members and veterans?
SGLI tops out at $500,000 and is tied to your service. Learn how SGLI, FSGLI, VGLI and VALife work and why some add a private term life policy.
Life insurance for single parents: how to protect your kids
A single parent's guide to life insurance: how much coverage to consider, guardians vs. beneficiaries, and why kids usually can't receive the money directly.